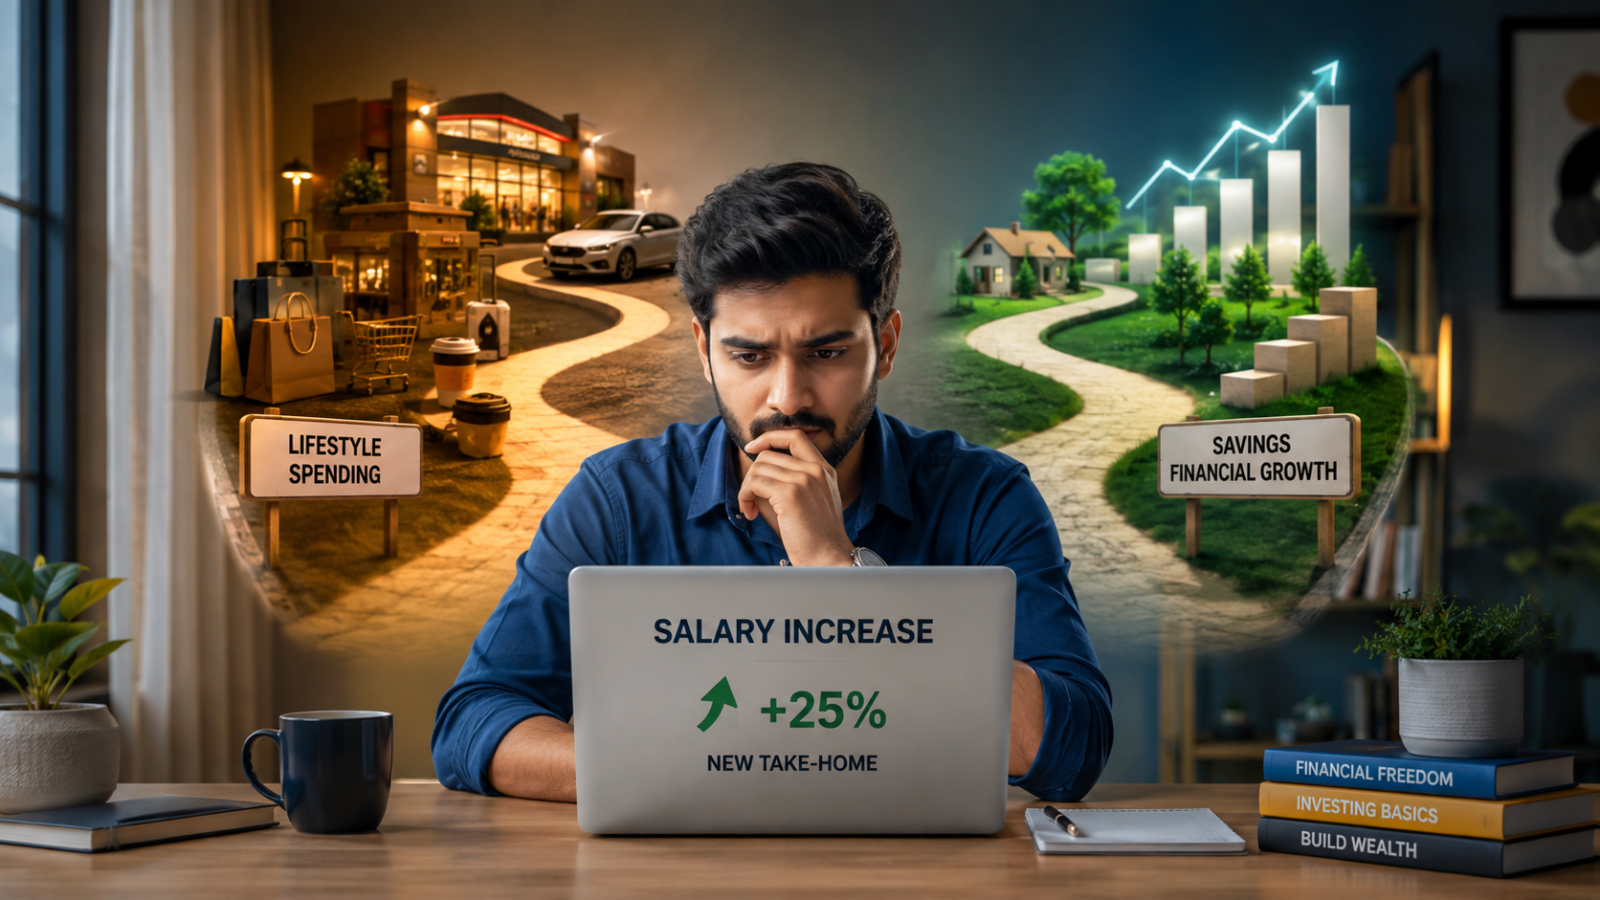
A salary hike is supposed to make life easier.
You expect to have more breathing room. Maybe save more, invest more, travel more or finally buy something you’ve been postponing.
But sometimes something strange happens.
Your salary increases.
Your lifestyle increases.
And somehow, your savings don’t.
You are earning more than you did two or three years ago, yet by the end of the month you still wonder:
“Where did all my money go?”
If this sounds familiar, the problem may not always be that you don’t earn enough.
Sometimes, the bigger problem is that your spending grows at almost the same speed as your income.
The Salary Hike That Disappeared
Imagine someone earning ₹50,000 a month.
They manage their expenses around that income because they know money is limited.
A few years later, their salary becomes ₹70,000.
Initially, that extra ₹20,000 feels like a major improvement.
Then things slowly change.
A better phone becomes affordable.
Eating out becomes more frequent.
Weekend spending increases.
A new subscription gets added.
A bigger vehicle starts looking reasonable.
Perhaps a new EMI enters the picture.
After some time, monthly expenses have also moved closer to ₹70,000.
The salary increased.
But the financial breathing room didn’t.
This is commonly known as lifestyle inflation.
What Is Lifestyle Inflation?
Lifestyle inflation happens when spending increases as income increases.
There is nothing wrong with enjoying some of the benefits of earning more.
The problem begins when every increase in income becomes a permanent increase in expenses.
For example:
Your salary increases by ₹10,000.
Instead of allowing at least part of that increase to strengthen your financial position, you gradually increase your lifestyle by almost the entire amount.
After a while, your new salary feels just as tight as the old one.
Then another salary hike becomes the solution.
And the cycle continues.
The Problem Isn’t Always One Big Purchase
Money doesn’t disappear only because of expensive purchases.
Sometimes it happens through many small decisions that eventually become normal.
Think about:
- More food delivery
- More online shopping
- Premium subscriptions
- More frequent cab rides
- Expensive weekend outings
- Bigger vacations
- Upgraded gadgets
- Higher phone or internet plans
- New EMIs
Individually, these expenses may not look dangerous.
But together, they can quietly change your monthly financial picture.
The important question isn’t:
“Can I afford this today?”
It is:
“Do I want this expense to become part of my normal lifestyle?”
The EMI Trap
A salary increase can make a new EMI feel comfortable.
Suppose you previously thought a ₹10,000 EMI was too much.
After your salary increases, the same EMI may suddenly look manageable.
Then another purchase comes along.
Another EMI.
Perhaps a credit-card payment gets added too.
Individually, each commitment may appear affordable.
Together, they reduce your future flexibility.
An EMI is not simply a monthly payment.
It is a commitment to use part of your future income for something you buy today.
Before taking a new EMI, ask yourself:
- Will I still be comfortable with this payment if my income doesn’t increase?
- Is this purchase genuinely necessary?
- What financial goal could be delayed because of this EMI?
- Am I buying this because I need it or because I can now afford it?
That last question can be surprisingly powerful.
Your Salary Increase Should Have a Job
When your income increases, don’t let the extra money automatically disappear into your lifestyle.
Give it a purpose.
For example, if your monthly take-home income increases by ₹10,000, you might decide that part of the increase goes toward:
- Emergency savings
- Investments
- Debt reduction
- A specific financial goal
- Lifestyle improvement
There is no universal percentage that works for everyone.
Your responsibilities, debt, family situation and goals are different.
The important part is deciding intentionally before the money gets absorbed by spending.
Try the “Pause Before Upgrade” Rule
The next time your salary increases, don’t immediately upgrade everything.
Give yourself some time.
Ask:
What do I actually need?
What would genuinely improve my life?
Am I buying this because I want it or because others have it?
Could this additional income strengthen one of my financial goals?
Will this new expense become a permanent monthly commitment?
A one-time celebration is very different from creating a new recurring expense.
Don’t Let Social Comparison Set Your Budget
Social media makes lifestyle inflation easier.
Someone buys a new car.
Someone posts an international holiday.
Someone upgrades their phone.
Someone shares an expensive restaurant every weekend.
You see the lifestyle.
You don’t see the complete financial picture behind it.
You don’t know their:
- Income
- Savings
- Investments
- Debt
- Family responsibilities
- Financial priorities
Comparing your financial life with someone else’s highlights can push you toward spending decisions that don’t fit your own goals.
Your budget should be based on your life, not somebody else’s Instagram feed.
What Does Financially Comfortable Really Mean?
Financial comfort doesn’t necessarily mean owning the newest phone, the biggest car or taking expensive holidays.
Sometimes financial progress looks much quieter.
It can mean:
- Having an emergency reserve
- Keeping debt under control
- Investing consistently according to your goals
- Having appropriate insurance
- Being prepared for unexpected expenses
- Not depending completely on your next salary credit
- Having enough flexibility to handle a difficult month
These things may not look impressive from the outside.
But they can create something much more valuable:
financial breathing room.
🧮 Want to See Where Your Salary Is Going?
Understanding the problem is only the first step.
Now calculate it.
Use the ArthVed Money Tools — Smart Budget Planner to enter your income, EMIs, household expenses, investments, family support and lifestyle spending.
It can help you see:
Monthly Income → Total Expenses → Savings → Savings Percentage
👉 [Use the ArthVed Smart Budget Planner]
Don’t guess where your money is going.
See the numbers.
A Simple Salary-Hike Strategy
The next time your income increases, try these five steps.
1. Calculate your actual increase
Look at your monthly take-home income rather than focusing only on annual CTC.
2. Decide the allocation first
Before changing your lifestyle, decide what the additional income should accomplish.
3. Allow yourself some lifestyle improvement
You worked for the increase.
Enjoying part of it isn’t a financial mistake.
The goal isn’t to stop enjoying your money.
The goal is to enjoy it without sacrificing your future.
4. Be careful with recurring commitments
A new EMI or subscription can continue for months or years.
Treat recurring expenses differently from one-time spending.
5. Review after three months
Ask:
“Has my financial position actually improved after my salary increase?”
If yes, you’re moving in the right direction.
If not, find out where the additional income went.
📘 Want to Build Better Money Habits?
Salary is only one part of your financial life.
Your money behaviour matters too.
If you’re a young Indian earner trying to understand saving, spending, EMIs, investing and everyday financial decisions, my book:
Money Mindset India
Behavior Rules for Salaried Indians (18–30 Years)
takes these everyday money questions deeper through practical, India-focused financial thinking.
The objective isn’t to promise quick wealth.
It’s to help you develop better money habits before small financial decisions become long-term problems.
📖 Explore the Book
[Learn More About Money Mindset India]
[Buy on Amazon]
Disclosure: The Amazon link may be an affiliate link. If you purchase through it, ArthVed Media may earn a commission at no additional cost to you.
The Question That Matters More Than “How Much Do I Earn?”
We often measure financial progress through salary.
But salary is only one number.
A more useful question is:
“How much of what I earn is actually improving my financial future?”
Someone earning ₹1 lakh a month and spending almost everything may have less financial flexibility than someone earning ₹70,000 while steadily building savings and investments according to their goals.
Income matters.
But what you do with that income matters too.
Your Next Salary Hike
So when your next increment arrives, celebrate it.
You worked for it.
Enjoy some of it.
Upgrade something if it genuinely improves your life.
But don’t allow the entire increase to become your new lifestyle.
Let a portion improve your today.
And let another portion improve your tomorrow.
Because the goal isn’t simply to earn more every year.
The goal is to become financially stronger every year.
That’s the difference between a higher salary and a better money life.
📚 Continue Your Money Journey
Want to understand your money better?
📘 Read: [Money Mindset India]
🧮 Calculate: [ArthVed Smart Budget Planner]
💳 Check: [ArthVed EMI Calculator]
🛡️ Plan: [ArthVed Emergency Fund Calculator]